Your rental property made $888 last month, but your bank balance increased by only $408. Both numbers are correct. Good bookkeeping services for real estate investors explain the difference by sorting your money into five buckets: income, operating costs, capital costs, debt, and equity.
In this example, the missing $480 was used to pay mortgage principal. It’s not an expense. It reduces your loan balance and builds equity in the property. Your profit and loss statement alone won’t show this difference.
If your profit and your bank balance never match, you’re not alone. This guide shows why, what bookkeeping services cost, and when hiring a bookkeeper is better than doing everything yourself.
What bookkeeping services for real estate investors include
Bookkeeping services for real estate investors track income and expenses, organize transactions, and check your records against bank statements. They help you get accurate reports for each property, financial statements for lenders, and organized records for your CPA.
These services include:
Tracking income by property and tenant
Recording expenses correctly and keeping repairs separate from improvements
Reconciling bank accounts, credit cards, and mortgages every month
Preparing profit and loss, balance sheet, and cash flow reports
Tracking security deposits and escrow accounts
Preparing a CPA-ready file for tax time
These services can help landlords, house flippers, and wholesalers. Their needs may differ, but the basic process is the same. Real estate accounting splits into two jobs. Bookkeeping records what happened, and your CPA handles tax planning and returns. We keep the books organized, so your CPA has accurate records to work with.
Why investors need it
Good bookkeeping for real estate investors helps you:
- Show which properties earn money and which cost you more than they earn
- Provide accurate financial records when applying for a refinance or selling a property
- Document every cost for your CPA
- Catch unexpected charges, such as an insurance premium billed twice
The five-bucket money map: where every dollar goes
Every dollar connected to a rental property belongs in one of five categories. When you record each amount correctly, your profit, cash flow, and equity become much easier to understand.
| Bucket | Examples | Where it shows |
|---|---|---|
| Income | Rent, late fees, pet rent | Profit and loss |
| Operating costs | Repairs, insurance, property taxes, management fees, mortgage interest | Profit and loss |
| Capital costs | New roof, HVAC, major rehab | Balance sheet, depreciated over time |
| Debt and deposits | Mortgage principal, loan balances, tenant security deposits | Balance sheet |
| Equity | Owner contributions and draws | Balance sheet |
We call this the five-bucket money map. Here’s the example behind our opening.
A rental property collects $2,400 in rent. The monthly mortgage payment is $1,650, made up of $890 in interest, $480 in principal, and $280 for escrow, which covers taxes and insurance. Assume the lender pays those bills the same month. You also pay a $192 property management fee and $150 for repairs.
| Measure | Calculation | Result |
|---|---|---|
| Profit | $2,400 – $150 repair – $192 fee – $280 taxes and insurance – $890 interest | $888 |
| Cash gained | $2,400 – $150 – $192 – $1,650 mortgage payment | $408 |
Lenders also look at net operating income (NOI). It’s rent minus repairs, fees, taxes, and insurance, before any mortgage payment: $2,400 − $150 − $192 − $280 = $1,778.
Subtract the $1,370 of interest and principal, and you’re left with $408 in cash.
The $480 difference is the mortgage principal. It pays down your loan, so it never affects your profit and loss. Your balance sheet shows it.
Owner draws work similarly. They reduce your equity and never belong on the profit and loss.
Residential rental buildings are generally depreciated over 27.5 years, and land isn’t depreciated. Your CPA sets the schedule, and the IRS depreciation guide explains the rules.
Want your own properties sorted this way? Book a free consultation, and we’ll show you where each dollar belongs.
How to set up your rental property books
Follow these five steps to get your rental property accounting organized.
Open a business bank account and credit card for each LLC, and keep personal spending out of those accounts.
Build a chart of accounts around the five buckets, then tag each property with a class or location.
Connect bank feeds and save receipts as you go.
Separate repairs from improvements. A repair keeps the property working. An improvement adds value or life. For example, fixing a roof leak is a repair and replacing the roof is a capital cost. Ask your CPA about situations that aren’t clear.
Keep a running total of operating costs for each property, so you can spot unusual expenses or a month when costs increase.
A well-organized chart of accounts is an important part of this setup. If you use QuickBooks, a QuickBooks setup with a class for each property lets you run profit and loss reports separately. This is what makes QuickBooks for rental property useful.
Security deposits should be recorded as liabilities, not income. Many small investors use the cash basis, which records money when it moves. Lenders and some managers want accrual, which records income when it’s earned.
Ask your CPA which method fits your situation. The IRS rental property guide explains what counts as rental income and expenses.
Mistakes that cost investors money
Accounting for rental properties usually goes wrong in a few predictable ways.
Personal and rental money in one account.
Major improvements may be incorrectly expensed instead of recorded as assets and depreciated.
Profit looks lower than it is.
Mortgage principal and security deposits may be missing or recorded incorrectly.
Mortgage and escrow balances can stop matching the actual records.
Payments to repair contractors may go unreported.
In our experience, an unreconciled escrow account is the one that can hide important errors. The IRS Form 1099 instructions explain the filing requirements for payments to contractors and other recipients.
Property manager statements: check them before recording transactions
If a property manager collects your rent, your bank deposit is not your rent. The deposit may already have deductions for management fees and repairs. Record the full statement, not just the deposit.
For example, the statement shows $2,400 rent, a $192 management fee, and a $150 repair. Your deposit is $2,058. Record each item separately, then check that the total matches the bank deposit.
Your income is $2,400, not $2,058. That $2,058 deposit, minus the $1,650 mortgage payment, is the same $408 from earlier.
Check for deposits that include a security deposit, which belongs in a liability account. Ask for the statement every month and review any amount that doesn’t match your records. Your manager should also maintain property trust records for the money they hold on your behalf.
Multiple LLCs and house flips
Real estate LLC accounting starts with keeping each business separate. Each LLC needs its own books, and each house flip should have its own project records.
Keep separate books for each LLC
Each LLC owns its own properties, so keep separate books for every entity. When money moves between LLCs, record it as “due to” and “due from,” not income or expense. You can then combine the financial information into one report to see the overall situation.
Record every owner contribution and draw as well so the balances remain accurate.
Give each flip its own project
Accounting for house flipping works best when you track every cost by project. That includes the purchase price, renovation costs, holding costs, lender draws, and sale proceeds. When the property sells, compare the closing statement with the bank deposit to make sure everything matches.
Your CPA determines how the costs should be treated for tax purposes.
Selling a rental through a 1031 exchange? Keep the exchange dates and paperwork with your books. Your CPA and the exchange intermediary handle the process.
The monthly close and the reports to expect
Each month’s close should end with a short set of reports you can read in minutes.
| Report | What it tells you |
|---|---|
| Profit and loss by property | Which rentals earn money |
| Rental property balance sheet | Loans, deposits, and equity |
| Cash flow statement | Where the cash went |
| Rent roll | Who owes what, and lease terms |
| Capital expense log | Improvements to depreciate |
Together, these are your rental property financial statements. Lenders often ask for a profit and loss statement and balance sheet when you apply to refinance a property.
You should review bank feeds every week and reconcile your bank, credit card, mortgage, and escrow accounts every month. Each quarter, check if your cash reserves are enough to cover upcoming expenses.
Track unpaid tenant balances and open vendor bills in one place, so nothing gets missed. Your CPA decides which expenses are deductible, and accurate books make rental property deductions easy to document.
This is general information, not personalized tax advice. Consult a licensed CPA or tax professional for your specific situation.
Software, DIY, or a bookkeeper?
Accounting software tracks your numbers, but a bookkeeper checks that the records are accurate. Many growing real estate investors use both.
Accounting software, like QuickBooks Online, handles income, expenses, and reports. Property management software adds tenant screening, rent collection, and maintenance requests. Some include accounting.
Real estate-specific accounting tools save setup time because they often come with a chart of accounts and reports designed for rental properties. However, they may cost more and offer fewer integrations with other tools.
Most investors we work with start on a spreadsheet, but it becomes harder to manage as mortgages, multiple LLCs, and house flips add more work. Start with QuickBooks classes. As the portfolio grows, move to property management software, and keep a bookkeeper for reconciliations and reports.
When should a real estate investor hire a bookkeeper?
Could you give a lender an accurate profit and loss statement for each property today?
Are you behind on reconciliations, or buying faster than you can track?
Did your last tax preparation process go smoothly?
Do you know your cash flow on each property?
Two or more no answers? Book a free consultation, and we’ll tell you what a cleanup would involve. If you hire, ask who sees your bank logins and how they reconcile your mortgage and escrow accounts.
An in-house hire adds salary, benefits, and training. Outsourcing scales as you add properties. A real estate CPA plans your taxes, and we hand your books straight to them.
What bookkeeping costs for real estate investors
Cost depends on how many properties, entities, and transactions you have, and how clean your books are today.
| Service level | Our typical monthly cost | Who it fits |
|---|---|---|
| Basic bookkeeping (categorizing, reconciliation, reports) | $100 – $300 | A few rentals, one entity |
| Full-service (adds bill pay, receivables, multiple entities) | $400 – $1,500+ | Larger portfolios, several LLCs |
| Cleanup of past months | Quoted after we review the file | Books behind or never reconciled |
Your first month with us
In the first 30 days, we clean up the past, set up the system, and close one clean month. The first thing we ask for is your mortgage statements, because that’s often where missing amounts or errors show up.
Free consultation and a secure upload of your statements (bank, card, mortgage, manager)
Mortgage and escrow check, matching each loan statement to your books first
Chart of accounts, property classes, and bank feeds
Bank and card reconciliation, oldest month first
Your first monthly close, with profit and cash flow side by side
Find out what your properties really earn
Choose the property with the messiest records and send us its statements for the last three months. Book a free consultation, and we’ll help you see how much it earns, where the numbers don’t match, and what needs to be fixed.
Ready to hand the books off? Our real estate bookkeeping services start with a review of your statements, and you’ll see the price before you commit.
Book your free consultation today, and let’s make sure every dollar is recorded correctly.
FAQs
How do I track rental property income and expenses?
Use a separate business bank account for each entity and connect it to your accounting software. Assign every transaction to the correct property, keep repairs separate from improvements, and reconcile your accounts every month.
How much does bookkeeping cost for real estate investors?
Our basic bookkeeping costs $100 to $300 a month, and full-service costs $400 or more. Cleanup of past months is quoted separately, and a free consultation gives you a written quote.
Can real estate investors outsource bookkeeping, and is it worth it?
Yes, bank feeds, mortgage statements, and property manager statements can all be shared online, allowing a remote team to manage your books. Outsourcing can be especially helpful when your books are behind, or you need accurate financial reports for a lender.
Can you handle multiple LLCs and work with my property manager's software?
In most cases, yes. We maintain separate books for each LLC and can combine the information into one report. We can also use statements and exported reports from your property manager to keep your records accurate.
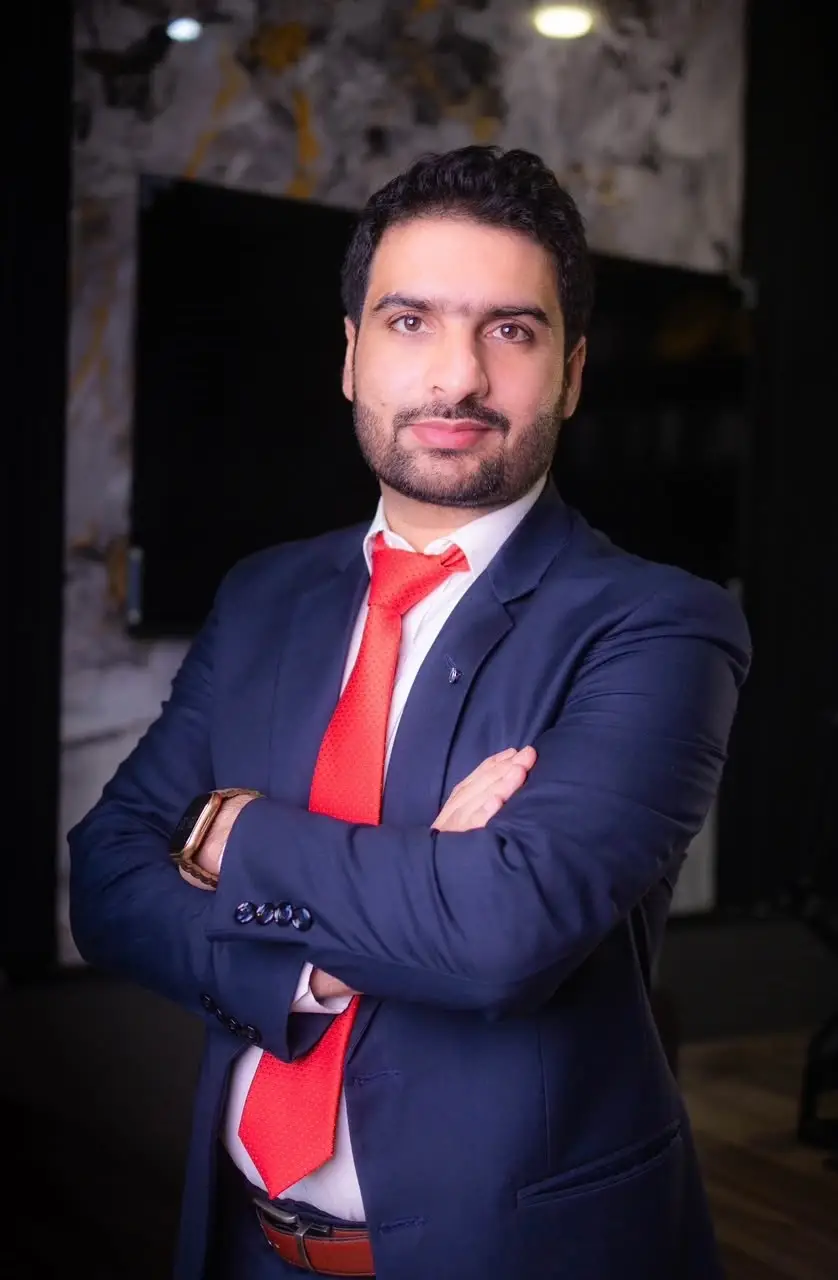
Meet Muhammad Aqib: Our Expert in Financial Planning and Analysis
He is the founder of Predawn Accounting and has more than six years of experience helping small businesses maintain organized financial records, improve reporting accuracy, and better understand their financial position.
He is a qualified Chartered Accountant from ICAP Pakistan, holds a BS in Accounting and Finance, is an ACCA Candidate, an FMVA Certified professional, has also earned a Financial Planning and Analysis certification from the Corporate Finance Institute (CFI) and is a Certified QuickBooks ProAdvisor with experience working across industries, including real estate, construction, e-commerce, SaaS, and marketing agencies.
Before founding Predawn Accounting in 2023, Mr. Aaqib worked with businesses across multiple industries, doing bookkeeping, financial reporting, financial modeling, fractional CFO, and other projects. He has also completed financial projects that helped businesses raise funding and improve financial operations.