A virtual accountant is an accountant who does your bookkeeping, financial reports, and month-end close from somewhere other than your office. They log into your QuickBooks or Xero file, pull your bank feeds, and do the same job an in-house accountant would. For most small businesses that costs somewhere between $300 and $1,500 a month, depending on how much is going on in the account.
If you only needed the definition, you have it. Most owners who search this term want something more practical, though. They want to know how the remote arrangement works on a Tuesday afternoon when a question comes up, what a fair price looks like, and how to tell a proper firm from one person with a laptop who might disappear in March.
I run a remote accounting practice. We’ve been doing books for US small businesses since 2023, entirely online, so I’ll write this from the inside rather than as a summary of other people’s articles.
What is a virtual accountant?
Same accountant, different chair.
A virtual accountant works through cloud accounting software, a document portal, email, and the occasional video call. Your data stays in QuickBooks Online or Xero under your own login. You give them accountant access and they work inside your file. Nothing gets copied to their hard drive and you never lose ownership of your own books.
The word “virtual” makes some people nervous, as if it means junior or unqualified. It doesn’t. The person doing your books remotely has sat the same exams and follows the same US GAAP rules as one who’d drive to your office. What changes is the overhead. No office lease, no commute, and that difference is most of the reason the monthly fee comes in lower.
Virtual accountant vs virtual bookkeeper
You’ll see the two terms used as if they’re interchangeable, and for a small business the overlap is honestly pretty large. The rough split: a bookkeeper records and reconciles what happened. An accountant does that and then tells you what it means, adjusts the entries that need adjusting, and prepares the statements you’d hand to a lender.
If clean, reconciled books are all you need right now, a bookkeeper is enough. If you also want someone who can explain why gross margin slipped in the second quarter, you’re looking for the accountant. I’ve written separately about the benefits of virtual bookkeeping if the bookkeeping side is where you are.
What does a virtual accountant do?
This is the question I get asked most, usually phrased as “so what would you actually be doing every month?” Here’s the list, roughly in the order it happens when a new client comes on.
Cleanup and catch-up first. If the books are behind, nothing else can start until the backlog is cleared. There’s no way around this and any firm that skips it is guessing.
Monthly bookkeeping. Transactions get categorized, every account gets reconciled to the bank statement, and the month gets closed. Closed means closed, so last month’s numbers don’t quietly change in April.
Financial statements. Profit and loss, balance sheet, cash flow, delivered on a schedule you agree up front, with someone available to walk through what moved and why.
Software setup and migration. Connecting QuickBooks or Xero to the bank properly, fixing a chart of accounts that’s grown 40 duplicate expense categories, and bringing older records across if you’re switching systems.
Payroll coordination. Recording payroll runs from Gusto or QuickBooks Payroll so wages, employer taxes, and withholdings land in the right place. Most firms don’t run payroll themselves; they make sure it’s booked correctly.
Tax-ready books. Organizing the year so your CPA gets a clean file instead of a shoebox. One thing worth knowing: a virtual accountant who isn’t a CPA or an Enrolled Agent won’t sign your tax return. That’s a different licence and a different role. I’ve covered the split in Bookkeeper vs CPA.
Once a business gets bigger, some firms add a controller review layer or fractional CFO work on top. The setup doesn’t change. The conversations get more strategic.
How does a virtual accountant work with you?
Less complicated than people expect. Here’s how a typical month runs.
In the first week you grant accountant access inside QuickBooks or Xero and make sure the bank and card feeds are connected. That’s it for setup. You don’t mail statements or export CSVs.
During the month, transactions flow in on their own. Your accountant categorizes them and reconciles the accounts. There will always be a few they can’t identify from the description alone, maybe five to fifteen a month, and those come back to you as a short list of questions. “What was the $340 at Home Depot on the 12th?” That kind of thing.
At month-end you get your reports plus a short note on anything unusual. If you have questions, they go by email or a fifteen-minute call. Receipts and invoices go through a portal or a tool like Hubdoc rather than being attached to emails, which matters more for security than convenience.
The owners who switch to this arrangement almost always tell me the same thing afterwards: the remote part, the bit they were worried about, turned out to be the easiest part. What they’d underestimated was how much time they’d been spending on it themselves.
How much does an online accountant cost?
Most firms charge a flat monthly fee. Here’s roughly where pricing sits in 2026:
| Business stage | Typical monthly fee | What’s usually included |
|---|---|---|
| Solo, under 50 transactions a month | $300 to $500 | Bookkeeping, reconciliation, basic reports |
| Small team, 50 to 200 transactions | $500 to $1,000 | Above plus payroll coordination and a monthly review call |
| Growing, 200+ transactions, inventory or several accounts | $1,000 to $1,500 | Above plus AR/AP management and custom reporting |
| Controller or fractional CFO support | $1,500 to $3,000 and up | Above plus forecasting, cash planning, board reports |
For comparison, the Bureau of Labor Statistics puts the median pay for a bookkeeping clerk at $50,670 a year as of May 2025. Once you add payroll taxes and benefits you’re near $70,000, and you haven’t bought software or a desk yet.
I’ve done that full comparison in outsourced bookkeeping vs hiring in-house, with the government sources laid out so you can check the arithmetic.
Three things push a quote toward the top of a range: transaction volume, how many people are on payroll, and how far behind the books are when you start. Catch-up work almost always gets quoted separately as a one-off project before the monthly fee kicks in. If that’s your situation, our guide to catch-up bookkeeping costs goes into what to expect.
Doing it yourself is cheapest in dollars and most expensive in evenings. Hiring in-house is the reverse. A virtual accountant sits somewhere between the two.
A small piece of advice from the quoting side of the table: ask for the quote itemized. “Bookkeeping, $600 a month” tells you nothing. “Up to 150 transactions, two bank accounts, monthly close, one review call” tells you exactly what you’re buying and makes it obvious when a competitor’s cheaper price has quietly left half of that out.
Virtual accountant vs in-house: which is right for you?
| Header label | Virtual accountant | In-house accountant |
|---|---|---|
| Cost | Flat monthly fee, scaled to volume | Salary, payroll tax, benefits, software |
| Expertise | A team with different specialties | One person’s skill set |
| Flexibility | Scale up or down month to month | Fixed cost, slow to change |
| Coverage | No gaps for sick days or vacations | Work stops when they’re out |
| Best for | Most businesses under roughly $10M revenue | High-volume firms that need someone on site every day |
The dividing line is volume. Once a business generates enough daily accounting work to fill a forty-hour week, hiring makes sense and I’d say so. Below that, you’re paying a full salary for a part-time workload, and the person you hire will spend their spare hours doing admin you didn’t hire them for. Our guide on who needs bookkeeping services has a short self-test if you’re not sure which side of that line you’re on.
Is your financial data safe with a virtual accountant?
Nearly every first call includes some version of this question, and it’s a reasonable one. You’re giving financial access to someone you may never meet in person.
What I’d say is that a well-run virtual firm is usually more secure than what it replaces. A filing cabinet has no encryption. A spreadsheet on someone’s personal laptop has no access log and, usually, no backup. Cloud accounting platforms have all three by default.
The IRS publishes data safeguards for anyone handling taxpayer information in Publication 4557, and a serious firm builds its process around that document.
The FTC Safeguards Rule separately requires financial service providers to have a written security plan and controls on who can access customer data.
Things to look for in practice:
- Accountant-level access inside your software rather than a shared login
- Read-only bank feeds instead of your online banking password
- A secure portal for documents, never email attachments
- Two-factor authentication on the firm’s side
- A straight answer to “who on your team can actually see my file?”
If a firm hesitates on any of those five, that tells you something.
Can ChatGPT do my bookkeeping?
Not on its own, and I’ll explain why rather than just say no.
AI tools are good at the explaining part. They can tell you what a journal entry should look like, draft a chart of accounts, or explain accrual versus cash in plain English. What they can’t do is connect to your bank, see your real transactions, or take responsibility when something’s wrong. In bookkeeping, “mostly right” is what costs you money at tax time.
Where AI has changed things is the routine layer. Categorization suggestions, receipt matching, and duplicate flags are built into QuickBooks and Xero now, and a good virtual accountant uses them. That’s part of why monthly fees are lower than they were five years ago. The judgement calls, the reconciliation you can actually trust, and the person who answers “why did this happen” are still human, and I don’t see that changing soon.
Use AI to understand your numbers. Use an accountant to produce them.
Virtual accountant for small business: the first 90 days
Every firm onboards a little differently, but a competent one follows a recognizable shape.
The first two weeks are diagnosis and cleanup. The accountant goes through your file, flags uncategorized transactions, months that were never reconciled, duplicate entries, and quotes the cleanup. If you’re more than a few months behind, this phase takes longer, and a firm that promises otherwise is going to cut corners you’ll pay for later.
Weeks three through six are about rebuilding the routine. Bank feeds get fixed, the chart of accounts gets tidied, and you get the first clean month-end close. This is usually the first time an owner sees reports they can trust.
By the end of the third month it’s steady state. The close lands on a predictable date, questions have dropped from dozens to a handful, and most owners I work with say they’ve got fifteen or more hours a month back.
The mistake I see most often is the owner who keeps “half the bookkeeping” to save money. It nearly always ends up costing twice: once for the service, once for the cleanup of the half they kept. Hand it over completely, read the reports monthly, and put the hours into the business.
How to choose the right virtual accountant
Six things to check, in the order I’d check them.
Credentials you can verify. CPA, CA, EA, or a proper bookkeeping certification, plus actual years of experience with businesses like yours.
US small business experience specifically. Sales tax, 1099s, estimated payments, and state rules are all US-specific. Someone whose clients are mostly in the UK or Australia will learn on your file.
They work in your software. Your QuickBooks or Xero account, under your ownership. If a firm insists on their own system, ask what happens to your data if you leave. The answer is often uncomfortable.
Pricing you can see. A range on the website and an itemized quote after they’ve looked at your books. Vague pricing usually rises.
Response time in writing. Ask what their turnaround is on a question. Within one business day is normal. No answer is your answer.
Reviews from real, named clients. Verified platform reviews, LinkedIn recommendations, or references you can phone.
And one more that isn’t on most lists: a good firm will tell you if you don’t need them yet. If someone pitches a $1,200 package before asking how many transactions you have, you’re hearing a sales script.
Not sure if remote would work for your books?
There’s a lower-effort way to find out than booking a sales call.
Send us three numbers: your monthly transaction count, how many bank and card accounts you have, and how many months behind you are (zero is fine). We’ll reply within one business day with a price range and a plain-English note on what we’d fix first. No meeting needed.
If the range makes sense we’ll set up a proper review of your file. If it doesn’t, you’ve spent one email. Our bookkeeping services page lists what’s included at each level if you want to compare before you write.
This article is general information, not personalized tax or financial advice. Every business is different. For your specific situation, talk to a licensed CPA or tax professional.
FAQ’s
How does working with a virtual accountant work?
You grant them access to QuickBooks or Xero and your bank feeds. They categorize and reconcile transactions monthly, deliver reports at month-end, and answer questions by email or a short call.
Is my financial data safe with a virtual accountant?
With a reputable firm, yes. Look for accountant-level software access, read-only bank feeds, a secure document portal, and two-factor authentication, and ask who on their team can see your file.
How much does a virtual accountant cost?
Most US small businesses pay $300 to $1,500 a month depending on transaction volume, payroll, and reporting needs. Catch-up work is usually quoted separately.
Can AI replace a virtual accountant?
Not yet. AI speeds up categorization and receipt matching, but it can't reconcile your actual accounts, take responsibility for accuracy, or explain what your numbers mean for your business.
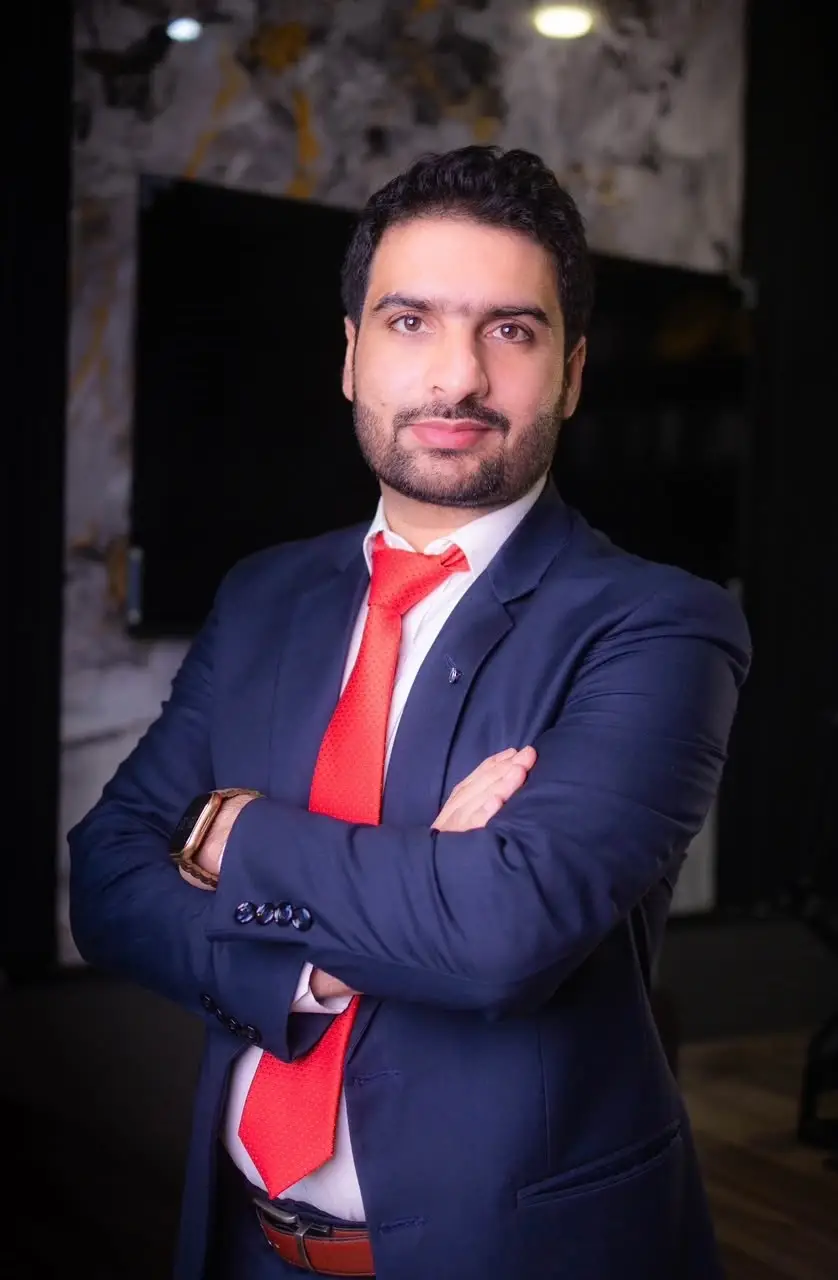
Meet Muhammad Aqib: Our Expert in Financial Planning and Analysis
He is the founder of Predawn Accounting and has more than six years of experience helping small businesses maintain organized financial records, improve reporting accuracy, and better understand their financial position.
He is a qualified Chartered Accountant from ICAP Pakistan, holds a BS in Accounting and Finance, is an ACCA Candidate, an FMVA Certified professional, has also earned a Financial Planning and Analysis certification from the Corporate Finance Institute (CFI) and is a Certified QuickBooks ProAdvisor with experience working across industries, including real estate, construction, e-commerce, SaaS, and marketing agencies.
Before founding Predawn Accounting in 2023, Mr. Aaqib worked with businesses across multiple industries, doing bookkeeping, financial reporting, financial modeling, fractional CFO, and other projects. He has also completed financial projects that helped businesses raise funding and improve financial operations.